Highlights
-
Parrish’s tight supply reading came alongside more listings and nearly steady sales.
-
Median and average prices both eased, indicating a softer completed-sales distribution.
-
Inventory expanded, increasing competition among sellers.
-
Marketing time barely changed and remained slower than the county.
-
The supply reading favored sellers, but prices and added inventory limited their practical leverage.
Market Conditions
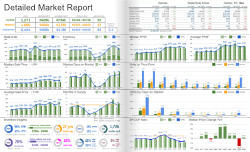
Parrish showed mixed conditions in September 2026. Its 2.9 months of supply suggested tight, seller-favored balance, yet inventory increased and prices declined. Nearly steady closings and a slower-than-county marketing pace caution against using supply alone to describe strong seller control.
The figures combine single-family homes, condos, townhomes, and villas, with year-over-year comparisons to September 2025.
The local supply reading compares with 3.5 months in Manatee County.
Pricing Trends
The median sale price declined 4.8%, from $394,000 to $375,000. The average declined 2.1%, from $437,000 to $428,000. The median marks the midpoint of sales; the average gives expensive transactions more influence.
The median declined 4.8%, and the average fell 2.1%. Both moved lower, contrasting with Manatee County’s increases. The local median remained below the county’s $420,000. Sales mix may contribute, so the figures do not establish uniform declines in individual property values.
Inventory Trends
Available inventory increased 17.0%, from 647 to 757 properties. Months of supply declined from 3.1 to 2.9.
The addition of 110 listings expanded buyer choice, against the countywide inventory decline. Lower supply months did not mean fewer listings. Because the source’s sales-rate calculation is not supplied, the two readings should be reported together without inventing a cause.
Market Pace
Closed sales declined 0.5%, from 204 to 203. Median days on market rose from 64 to 65 days. Closed sales measure completed transactions rather than new contracts.
The 65-day median was 12 days longer than the county’s 53 days and rose one day year over year. Closings declined only 0.5%. Activity and speed were nearly steady, while the larger inventory pool increased competition among listings.
What This Means for Buyers
Buyers have more homes to compare despite the tight supply reading. Use lower median and average prices as context for comparable sales rather than assume a uniform discount. The slower local pace allows careful evaluation, with urgency determined by the specific property’s competition.
What This Means for Sellers
Sellers face additional listing competition and slightly lower completed-sale prices. Price against current comparable closings, prepare the home carefully, and allow for marketing time longer than the county norm. The 2.9-month reading does not remove the need to compete on value.