Highlights
-
South Sarasota County tightened mainly through a large reduction in available listings.
-
Median and average prices rose modestly, contrasting with the county’s divided pricing results.
-
Inventory contracted sharply, leaving supply below the countywide level.
-
Marketing time shortened substantially while completed sales increased only slightly.
-
Sellers gained a firmer position, but the modest price gains did not imply unrestricted leverage.
Market Conditions
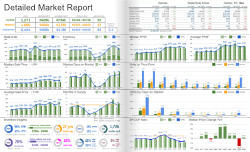
South Sarasota County moved toward seller-leaning balance in September 2026. Its 3.3 months of supply and 50-day median marketing time were tighter and faster than the county overall. The main shift came from fewer listings and shorter selling times rather than a large increase in completed transactions.
The figures combine single-family homes, condos, townhomes, and villas, with year-over-year comparisons to September 2025.
The local supply reading compares with 3.7 months in Sarasota County.
Pricing Trends
The median sale price increased 2.1%, from $375,000 to $383,000. The average increased 4.9%, from $453,000 to $475,000. The median marks the midpoint of sales; the average gives expensive transactions more influence.
The median increased 2.1% and the average rose 4.9%, a steadier picture than Sarasota County’s lower median and sharply higher average. The local median remained below the county’s $428,000. Both measures rose, but differing property mixes still prevent a uniform appreciation conclusion.
Inventory Trends
Available inventory declined 27.9%, from 2,649 to 1,911 properties. Months of supply declined from 4.7 to 3.3.
The reduction of 738 listings was substantial. Current supply was below September 2024’s 5.0 months, but above September 2019’s 2.9 months. The southern half of the county therefore had much less excess choice than in recent Septembers while remaining outside an extreme shortage.
Market Pace
Closed sales increased 2.7%, from 475 to 488. Median days on market fell from 82 to 50 days. Closed sales measure completed transactions rather than new contracts.
The median selling period shortened by 32 days and was six days below the county’s 56-day reading. Sales increased only 2.7%, much less than the county’s 33.8%. Local improvement centered on speed and reduced competition among listings rather than a comparable surge in closings.
What This Means for Buyers
Buyers should expect fewer alternatives and less time to evaluate a well-priced match than last September. Compare properties within the same community and category to judge the modest price increases. Keep negotiation tied to recent sales and the competition for the specific listing.
What This Means for Sellers
Sellers benefit from fewer competing listings and a much shorter median marketing period. Modest price gains support measured expectations rather than aggressive increases. Price near current comparable sales, prepare the home carefully, and plan for a market that is faster but still selective.