Highlights
-
North Manatee County’s lower supply reading coincided with more listings, keeping conditions mixed.
-
Median and average prices both eased slightly.
-
Inventory expanded against the countywide decline, giving buyers additional alternatives.
-
Completed sales were nearly steady while marketing time shortened.
-
Sellers faced more listing competition even though the reported balance leaned toward them.
Market Conditions
North Manatee County showed mixed, seller-leaning balance in September 2026. Its 3.1 months of supply was below the county, but available listings increased rather than contracted. The area north of the Manatee River therefore offered more buyer choice while recording a lower supply reading and a faster completed-sales pace.
The figures combine single-family homes, condos, townhomes, and villas, with year-over-year comparisons to September 2025.
The local supply reading compares with 3.5 months in Manatee County.
Pricing Trends
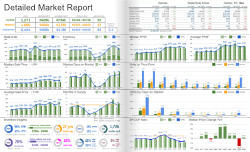
The median sale price declined 1.8%, from $388,000 to $381,000. The average declined 1.8%, from $447,000 to $439,000. The median marks the midpoint of sales; the average gives expensive transactions more influence.
The median declined 1.8%, and the average also fell 1.8%. Both measures showed modest softness in the completed-sales distribution, contrasting with countywide increases. The median remained below the county’s $420,000. Changes in the mix of homes sold may still affect these small movements.
Inventory Trends
Available inventory increased 11.8%, from 1,102 to 1,232 properties. Months of supply declined from 3.5 to 3.1.
The addition of 130 listings set the area apart from the county’s 10.3% inventory decline. Inventory and months of supply need not move together because supply depends on the source’s sales-rate calculation. The lower supply reading should not be described as a reduction in the actual number of available homes.
Market Pace
Closed sales declined 1.0%, from 305 to 302. Median days on market fell from 57 to 51 days. Closed sales measure completed transactions rather than new contracts.
The 51-day median was two days shorter than the county’s 53 days and improved six days year over year. Closings declined only 1.0%, indicating nearly steady completed activity. The main differences were additional listing choice and a modestly faster selling period.
What This Means for Buyers
Buyers have more listings to compare than last September, despite the lower supply reading. Use the modest price declines as context for comparable sales rather than assume a fixed discount. A faster marketing period supports prompt evaluation of a good match without treating the entire area as short of choices.
What This Means for Sellers
Sellers face additional competing inventory, even though the reported supply reading leans toward them. Nearly steady closings and slightly lower prices call for realistic expectations. Price against similar completed sales and prepare the property to stand out from a larger pool of active listings.