Highlights
-
Venice and North Venice shifted into a tight, seller-favored market as inventory declined sharply.
-
Median and average prices remained stable, showing little broad movement in completed-sale values.
-
Homes sold much faster than they did last summer despite a modest decline in sales.
-
Buyers faced less supply than they did across Sarasota County overall.
-
Sellers benefited from reduced competition, but stable pricing showed that buyers remained disciplined.
Market Conditions
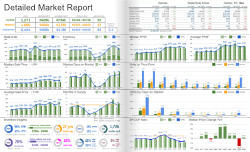
Venice and North Venice tightened substantially in August as available inventory contracted. Closed sales declined 2.6%, but inventory fell 32.3%. The much larger reduction in supply lowered months of inventory from 4.2 to 2.6 months.
That moved the market from balanced conditions into seller-favored territory. Sarasota County carried 3.6 months of supply, making Venice and North Venice tighter than the countywide market.
The shift did not result from accelerating sales. Instead, fewer available homes changed the balance between buyers and sellers. Buyers had less selection, while sellers faced substantially less competition.
Pricing Trends
The median sale price increased 1.3%, rising from $385,000 in August 2025 to $390,000 in August 2026. This small change indicates that pricing near the middle of the market remained stable.
The average sale price declined 0.9%, from $468,000 to $464,000. With the median slightly higher and the average nearly unchanged, the figures do not support a conclusion that prices moved significantly in either direction.
Venice and North Venice remained more affordable than Sarasota County overall, where the median reached $412,000 and the average was $603,000. Differences in property type, age, location, and proximity to the coast can still produce wide variations within the local market.
Inventory Trends
Available inventory declined from 1,101 homes last August to 745 this year, removing 356 listings from the market.
Months of supply fell from 4.2 to 2.6 months. Buyers had fewer options, while sellers competed against nearly one-third fewer listings. Supply remained above the extreme shortage of 2021, but conditions became much tighter than they were last summer.
Market Pace
Homes sold substantially faster even though fewer transactions closed. Median days on market fell from 89 to 60 days, while sales declined from 233 to 227.
The 29-day improvement brought Venice and North Venice closer to Sarasota County’s 55-day median. Well-positioned homes found buyers more efficiently, but the stable pricing measures show that buyers did not abandon their focus on value.
What This Means for Buyers
Buyers have fewer homes to choose from and may need to act more quickly when a strong property appears. Stable pricing provides some protection against broad upward pressure, but reduced inventory limits alternatives. Recent neighborhood-level sales should guide offers, especially when comparing newer communities with established areas.
What This Means for Sellers
Sellers benefit from much lower inventory and a faster market. However, nearly unchanged pricing shows that tighter conditions do not automatically support a higher asking price. Accurate pricing, good preparation, and realistic expectations remain essential.